
Why Russia’s harsh 1% crypto cap actually protects bank customer assets

The Bank of Russia has proposed a 1% crypto capital cap, limiting lined crypto and foreign-digital-instrument threat to a bank’s personal funds whereas leaving some consumer custody positions exterior the brand new calculation.
The Sept. 18 proposal would create N31 for particular person credit score establishments and N32 for banking teams on a consolidated foundation. Each ratio compares lined publicity with the related establishment’s capital, not its whole assets. The guidelines stay in draft type.
The two-level construction topics each a bank and its wider group to the identical proposed share ceiling. N31 makes use of the person establishment’s personal funds, whereas N32 makes use of consolidated group capital, holding the measurement tied to the entity that carries the lined threat.
What the 1% crypto capital cap captures
The draft regulation reaches past cash held outright. Its numerator consists of direct and oblique investments, derivatives tied to crypto costs, and devices akin to loans, bonds, ensures, repos and credit score traces when their settlement or worth relies on crypto or overseas digital devices.
Banks would obtain restricted recognition for hedges. Long and brief positions could also be netted solely inside the draft’s qualifying lower-risk class, which imposes situations tied to the asset, settlement and maturity in addition to freezing and liquidity threat. Direct holdings and different higher-risk exposures are measured extra conservatively and can’t be absolutely neutralized by an offsetting place.
The remedy of customer assets activates who bears the loss if assets are seized or transactions are restricted. A custody place enters N31 or N32 when the bank, or a digital depository in its group, is responsible for that loss. If the bank doesn’t bear that accountability, the consumer place is excluded from the 2 1% ratios.
That exclusion doesn’t take away the place from prudential remedy. For lined bank and group capital-adequacy calculations, the draft assigns non-liable consumer custody positions a 50% threat weight. Own-account publicity and consumer positions for which the bank is liable obtain a 1,250% threat weight.
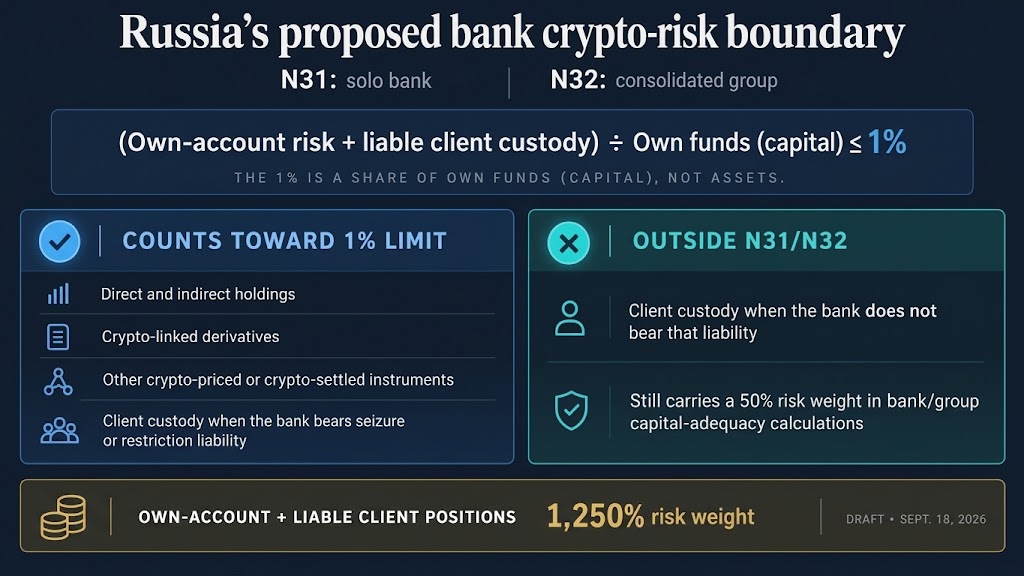
The distinction permits custody with out routinely treating each customer asset because the bank’s personal publicity, supplied the establishment doesn’t bear the desired seizure or restriction legal responsibility. It concurrently locations a good capital-based constraint on direct holdings and different crypto-linked threat carried by the bank.
The ratios are a part of Russia’s broader crypto-market rulemaking, a framework CryptoSlate has beforehand described as still being completed. The central bank plans official publication within the fourth quarter of 2026, with the necessities taking impact 10 days later. Banks are anticipated to start reporting instrument turnover and N31/N32 values in January 2027, though detailed varieties are nonetheless being developed.
The publish Why Russia’s harsh 1% crypto cap actually protects bank customer assets appeared first on CryptoSlate.


